Life insurance is often viewed as a safety net, but did you know it can also offer significant tax advantages? In Switzerland, understanding how life insurance can benefit your tax situation might just be what you need to take control of your finances. Let’s dive into the details, shall we?
The Basics of Life Insurance in Switzerland
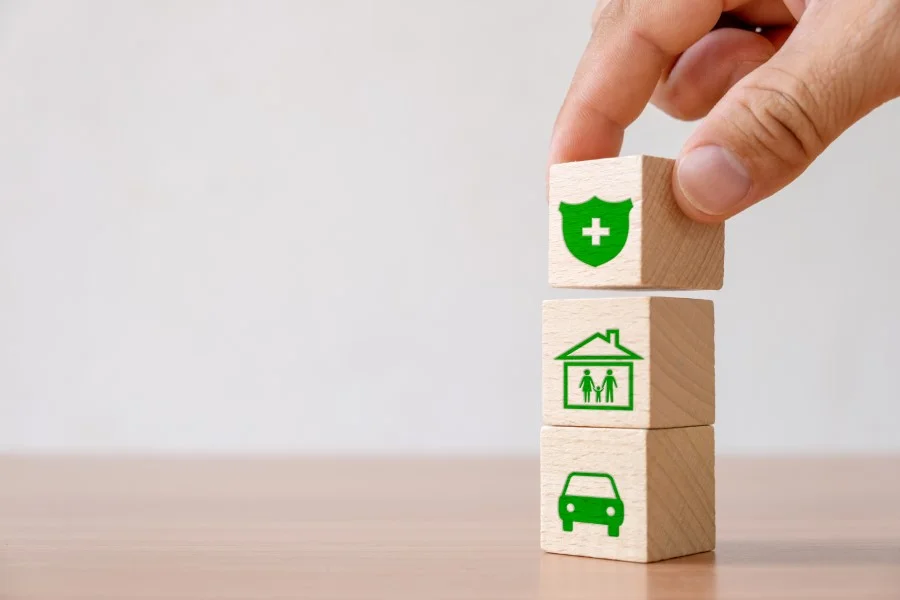
In Switzerland, life insurance comes in various forms, each designed to meet different needs. The two primary types include:
- Term Life Insurance: Provides coverage for a specified period.
- Whole Life Insurance: Offers lifelong coverage and often includes investment components.
While both have their own perks, we’ll focus on how they can optimize your taxes.
Tax Benefits for Policyholders
One of the standout features of life insurance in Switzerland is the potential tax benefits. Here’s a breakdown:
1. When premiums may qualify for a deduction
Premiums paid into an eligible Pillar 3a arrangement can qualify for a deduction within the applicable allowance. An ordinary Pillar 3b premium does not automatically create an additional deduction: general insurance allowances, existing cover and cantonal rules matter.
2. Tax treatment of death benefits
Do not assume every life-insurance death benefit is tax-free. Treatment depends on the policy, whether it is Pillar 3a or 3b, the beneficiary and the canton. Ask for the relevant tax position before choosing a structure or naming beneficiaries.
An illustrative example: The Jensen Family
Illustrative scenario: names, amounts and outcomes describe a hypothetical example rather than a verified client result.
Illustrative example: a Zurich family compares a protection policy with a savings-linked policy. A CHF 5,000 premium does not by itself establish a CHF 1,250 tax saving, and a CHF 500,000 benefit is not automatically tax-free. The structure and the family’s actual tax position determine the outcome.
This example highlights how smart financial planning can yield substantial benefits and security, particularly for young families.
Practical Tips for Maximizing Tax Benefits
So, how can you make the most of these tax advantages?
1. Research Your Canton’s Regulations
Tax laws can change and differ significantly across cantons. Be sure to check local guidelines in cities like Lausanne or Geneva to understand how they apply to you.
2. Consult a Financial Advisor
Engaging with a financial advisor who specializes in Swiss tax law can provide personalized advice tailored to your situation. They can help you navigate the complexities and find the best solutions for your needs.
3. Keep Your Policy Updated
As your life circumstances change, so might your insurance needs. Regularly review your life insurance policy to ensure it aligns with your financial goals.
Taking Action Now
Understanding the tax advantages of life insurance in Switzerland can significantly impact your financial future. Whether you live in Zug, Zurich, Lausanne, or Geneva, there are opportunities waiting for you to explore.
Why not take the first step today? Review your current insurance policy, or consult with a financial advisor to discuss how life insurance can help optimize your tax situation. Educate yourself, plan wisely, and secure your family’s future with the potential benefits that life insurance can offer.
In the ever-changing landscape of personal finance, a little proactive planning goes a long way. Start researching, and who knows? You might find hidden treasures in your financial strategy!