Renting a home?Check tenant damage and lost keys.

A little reassurance for everyday life. English-speaking advice on personal liability cover for tenants, families and expats in Switzerland.
Personal liability, explained
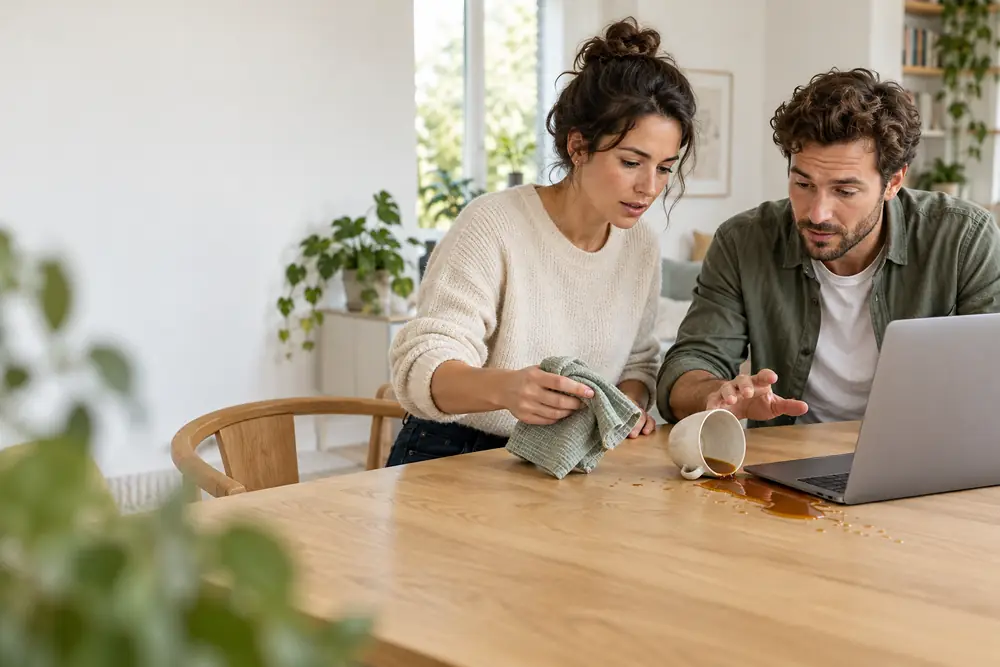
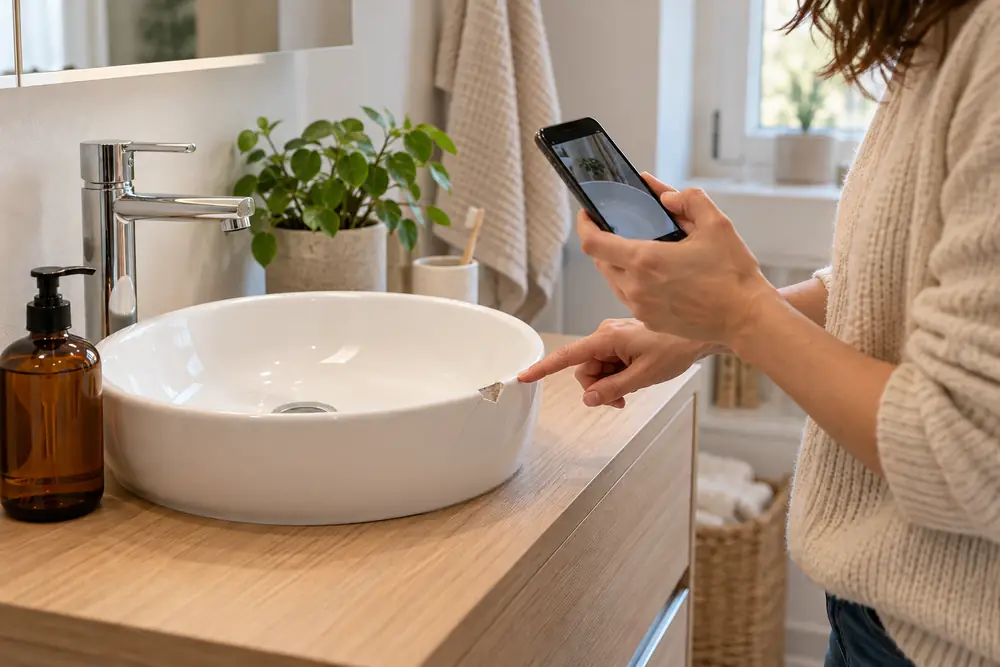
You knock over a friend’s laptop. A dropped bottle cracks the basin in your rented flat. Everyday accidents can lead to a claim for compensation.
Personal liability insurance can cover your legal responsibility for injuring someone or damaging their property, subject to the policy. It can also help challenge a claim you do not owe. It is often called private liability, Privathaftpflicht or responsabilité civile privée.
Private cover is generally voluntary in Switzerland, although landlords may require it. Specific activities can bring additional obligations.
New to Switzerland? See ETH Zurich’s overview for newcomers.
Cover can meet valid claims for injury or damage you cause to others.
The insurer can also defend unjustified claims within the policy.
Check who is insured, the limit, your excess and any optional benefits.
Two covers, two purposes
Personal liability and home contents are often sold together. They still do different jobs. Start with whose loss you are trying to insure.
For covered claims made against you in your private life.
Check exclusions and special limits, especially for borrowed items, keys and vehicles.
For the belongings you own, such as furniture, clothes and electronics.
A combined package can be convenient. Compare the cover for each part separately.
Make it work for you
Your landlord may ask for a liability insurance certificate before you move in. Arrange the start date around your tenancy, and keep a copy of the policy and handover report.
Liability insurance does not replace your rental deposit or guarantee that every deduction will be reimbursed. It responds to a covered liability claim under its own terms.
A household changes. Tell your adviser about a partner moving in, children living away to study, a new pet or a hobby that needs specific protection.
Tell us about cycling, skiing, drones, paid side work and time spent abroad. Specialist activities and professional risks can fall outside ordinary private cover.
For a local example, Geneva’s guidance for dog owners includes liability insurance documentation. Check the rules where you live.
Compare the everyday details as well as the annual premium. A low price is only useful if the policy matches the people and activities you want to insure.
A serious injury claim can include long-term financial consequences. Compare the available limits and any lower limits for particular benefits.
Check the amount you pay yourself. Tenant damage or optional benefits can have a different excess from the standard cover.
Ask about gross-negligence protection, keys, borrowed vehicles and hobbies. Check conditions rather than relying on a benefit’s name.
Advice built around you
Your cover should make sense for your home and the way you live. We help you compare the practical details, from the people on the policy to the extras you may actually use.
Our English-speaking team in Zug and Geneva supports residents, families and expats in Zurich, Lausanne and across Switzerland. Bring your current policy or tenancy requirements, and we can start there.
Based on 80 reviews

Exceptional Service and Financial Guidance! I have been working with SwissPrime International for the past four years for my tax returns, and I cannot recommend them highly enough. Their services are consistently outstanding, prompt, and incredibly helpful. What truly sets SwissPrime apart is their approachability and willingness to have open, transparent discussions. Beyond just handling my annual tax filing, they have provided me with invaluable, personalized insights into enhancing my retirement plan year over year. They also took the time to offer excellent Swiss financial education, which has been a massive advantage in navigating the local financial landscape. If you are looking for a reliable, knowledgeable, and proactive partner for your financial and tax needs, SwissPrime International is the way to go!

Ever since I moved to Zug, Swiss Prime has helped me with my taxes. They have always been very forthcoming, professional, and helpful with taxes, declarations, and pension planning.

Our family has been a client of Swiss Prime for over ten years. t's always a pleasure working with them. Fast, efficient and accurate service.

I have had the pleasure of managing my tax returns and insurance policy discussions with the team over the last 6 years. Always clear, always helpful and have a vast knowledge of the market to advise.

Super service, immer schnelle und zuverlässige Bearbeitung! Inklusive guter tipps

Philip Hüsler assisted me for my tax submissions agter moving to Canton Zug. I am extremenly impressed with his professional and timely service. Extremely good value and greatly appreciated..

As an expat, dealing with taxes in Switzerland can be quite complex, so having the right support makes a huge difference. I had a very positive experience working with this team, especially Philip Huesler on my tax matters. They are highly professional, knowledgeable, and very responsive. Whenever I had questions—whether about the tax process, documentation, or specific situations—I always received clear and helpful answers in a timely manner. Their guidance made the entire process much smoother and gave me confidence that everything was being handled correctly. I can highly recommend their services, especially for expats looking for reliable and professional tax support.

The Swiss Prime team (Philip in particular) has been supporting my family tax filings for the last four years. Always proactive in defining requirements and setting timelines, clear in communications and documentation needs and at the end, a timely and clean filing. They also make time for calls to clarify any questions or requests from the Swiss tax authorities. And, they handle complexity well, given my tax filing spans two countries. Daniel from the team has been a long-time advisor for my other investment needs and has always been objective and supportive with his expert recommendations.

I have been using Swiss Prime International’s services for several years and I am consistently very happy with them. The team is highly responsive, extremely knowledgeable and always very kind and professional. They take time to understand my needs and provide clear, reliable support. It is a pleasure working with a company that delivers such a high standard of service year after year. Highly recommended!

I’ve been working with Swiss Prime advisors for a while now, and I couldn’t be more satisfied with the service. They are incredibly knowledgeable, detail-oriented, and always up to date with the latest regulations, no matter if it's tax, investments or insurance related. They’re also very responsive and easy to reach whenever I have questions. I always feel confident that my finances are being handled accurately and efficiently. Overall, a reliable, professional, and trustworthy expert who genuinely cares about their clients. Highly recommended to anyone looking for peace of mind when it comes to handling their finances.
Answers before you apply
Clear answers to help you choose with confidence.
Private liability insurance is generally voluntary, although your tenancy agreement may require it. Dog ownership and some activities can bring specific requirements. Check the applicable cantonal rules and any certificate your landlord or activity provider needs.
No. Liability concerns covered claims against you for injury or damage to others. Home contents concerns your own belongings and the events insured by that contract. They may share one policy document but remain separate types of cover.
Certain accidental damage can be covered. Normal wear and tear, deliberate alterations and gradual damage are treated differently. Check the tenant-damage excess, pet extensions and key cover. Send any landlord claim to your insurer for assessment.
That depends on the policy’s definition of insured people and the household details declared. Confirm everyone who needs cover, including children studying elsewhere. Do not assume a family or multi-person policy covers every person or damage they cause to each other.
Yes, subject to the insurer’s eligibility rules. Bring details of your Swiss address, household and existing policies. Check for gaps or overlap with overseas cover, particularly if you retain a home abroad or expect to move again.
Many policies extend cover to private activities abroad, but territory, trip duration, residence and activity restrictions vary. Check before relying on it for a long stay or a move. Motor vehicles and specialist activities may need separate arrangements.
Not automatically. Ask specifically about damage to a borrowed vehicle, the owner’s excess and loss of no-claims bonus. An occasional-driver extension can have restrictions on regular use, household vehicles, rental cars and car sharing.
No. Defending an unjustified liability claim is part of the liability cover provided by the policy. Wider disputes, such as employment or contractual disagreements, fall outside that purpose and may need separate legal protection insurance.
A helpful first conversation
Tell us who needs cover, whether you rent or own, and any pets, hobbies or borrowed vehicles to consider. We can help you prepare a useful comparison.
Alpenstrasse 14, 6300 Zug, Switzerland.
Chemin du Pommier 42, Case postale 53,
1218 Le Grand-Saconnex, Switzerland.
Thank you. We have received your message and will be in touch as soon as possible.
Insights & guides
Practical reading to help you make informed decisions about your cover.
Living in Switzerland with an international lifestyle? Review health, travel, liability, life and income risks across borders without duplicating cover.
Read articleConnect insurance choices with your wider financial plan, including household risks, retirement goals, costs and the cover you already hold.
Read articleUnderstand Swiss insurance oversight and consumer responsibilities, and learn which policy information to review before taking out cover.
Read article| What to compare | Personal liability | Home contents |
|---|---|---|
| The main question | Are you legally responsible for someone else’s loss? | Have your own insured belongings been damaged or stolen? |
| A friend’s laptop | An accidental damage claim may be covered. | Your contents policy is not normally the answer for their laptop. |
| Your own sofa | Damage to your own property is generally excluded. | Cover depends on the insured event and any accidental-damage extension. |
| A rented washbasin | Accidental tenant damage may be covered. | The landlord’s fixed fitting is not your household contents. |
| What to compare | Insured people, liability limit, excesses and exclusions. | Insured value, covered events, item limits and excesses. |